Market Analysis
Atlanta, GA Housing Market 2026: Prices, Trends and Forecast Across a 29-County Metro
Atlanta, GA housing market 2026: metro price ranges by county, rising inventory, investor-owned rentals, the homestead tax change, insurance costs, and a forecast.
Atlanta, GA Housing Market 2026: Prices, Trends and Forecast Across a 29-County Metro
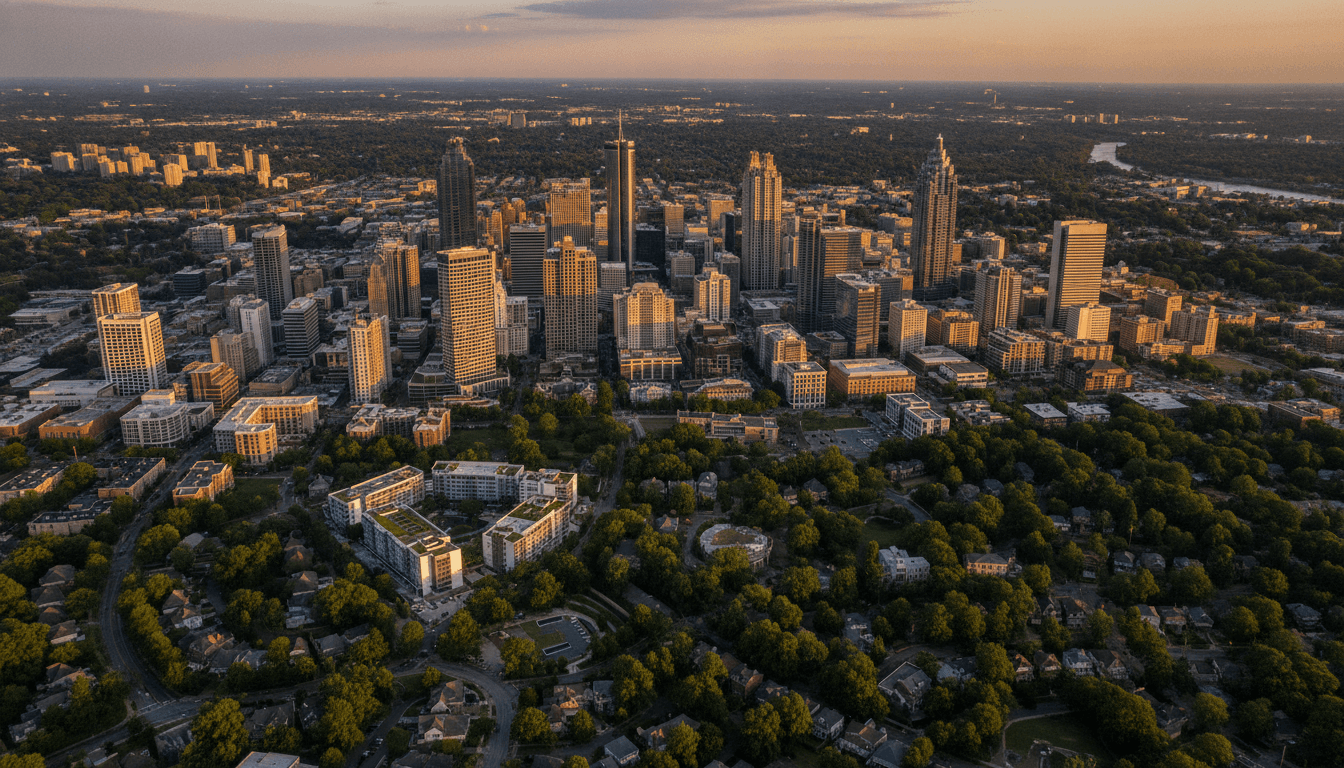
There is no single Atlanta price worth quoting. The metro spans 29 counties and runs from Cartersville down past Griffin, so a renovated bungalow in Kirkwood and a new four-bedroom in Paulding County can sit $300,000 apart while landing in the same monthly market report.
The Atlanta, GA housing market in 2026 is calmer than the headlines make it sound. Prices across most of the metro are close to flat year over year, listings take longer to go under contract than they did in 2023, and sellers are paying for rate buydowns to get deals closed. Buyers have not disappeared, they have just gotten choosier and more willing to walk away.
Three local forces are shaping this year more than mortgage rates are. Investor-owned rental houses still hold a large share of the southern counties, a change to Georgia's homestead rules reset what many owners pay in property taxes, and builders keep delivering inventory that competes directly with resale listings in the same school zones.
What Homes Are Selling For Right Now
Typical sale prices across metro Atlanta sit in the high $300,000s to low $400,000s, and that number moves very little from quarter to quarter these days. For a metro with this much corporate employment, that still buys more square footage than most large Sun Belt markets. It also hides an enormous spread between submarkets.
The direction of travel has been sideways. Prices ticked up in the spring selling season, gave some of it back over the summer, and are running within a few percent of where they were a year ago. Anyone waiting on a dramatic Atlanta correction has been waiting since rates first jumped.
What has changed is the shape of a deal rather than the sticker price. Sellers who once fielded five offers now negotiate repairs, cover closing costs, and buy the rate down a point. The price on the county record looks similar to 2023, while the concessions behind it do not.
Inside the Perimeter
Intown neighborhoods hold the highest prices per square foot in the metro, and the gap has widened since the BeltLine's Eastside and Southside trails connected more of the corridor. Homes within a short walk of a completed trail segment in Grant Park, Reynoldstown, or Summerhill carry a premium over comparable houses six blocks off it.
Buckhead, Morningside, and Virginia-Highland remain the top of the market, where seven-figure sales are ordinary rather than notable. Further west, Grove Park and parts of the Westside have seen the fastest percentage price growth in the city, driven by renovation activity and proximity to the Westside Park reservoir project.
The Northern Counties
Cobb, north Fulton, Forsyth, Cherokee, and Gwinnett carry the deepest inventory of large homes on large lots, and they draw most of the relocation demand tied to the GA-400 and I-75 job corridors. Alpharetta, Johns Creek, and Milton price well above the metro average. Kennesaw, Acworth, and much of Gwinnett land closer to it.
Commute math drives a lot of these decisions. A house in Cumming and a house in Marietta may cost the same, and the difference in a daily drive to Perimeter Center or Midtown can be 25 minutes each way.
South of the City
Clayton, Henry, south Fulton, and Fayette counties offer the lowest entry prices in the metro, often $100,000 or more below the northern suburbs for a similar house. Fayetteville and Peachtree City hold their own tier because of the Trilith studio campus and the golf cart path network.
Inventory turns more slowly down here, partly because so much of it is investor-owned and partly because appraisals lag in neighborhoods with thin recent sales. Buyers with patience find the best value in the metro in these counties.
Inventory Is Up and Days on Market Tell the Story
Active listings across metro Atlanta have climbed back to levels the region has not seen since before the pandemic, and the rebound has been sharper in the outer counties than intown. Homes that would have sold in a weekend in 2021 now sit for 40 to 60 days in many submarkets. Price reductions have become a routine part of the listing strategy rather than a signal of trouble.
Leverage is not uniform, and sellers should not assume the worst. A well-priced, updated three-bedroom in a strong school zone with a new roof still draws showings in the first week, sometimes with competing offers. The listings that stall are the ones priced against a neighbor's 2022 sale, or the ones carrying deferred maintenance the photos cannot hide.
Rental supply has softened the ownership calculus too. Metro Atlanta absorbed a large wave of new apartment deliveries, concessions on lease-ups are common, and that gives would-be buyers a real reason to wait another year without feeling punished for it.
The Investor Footprint Nobody Priced In
Metro Atlanta remains one of the most institutionally owned single-family rental markets in the country, concentrated in Clayton, Henry, south Fulton, Douglas, and parts of Gwinnett. In some subdivisions built between 2000 and 2008, corporate landlords hold a double-digit share of the houses. That reality changes how a street trades.
Two effects show up in practice. Rental-heavy subdivisions often show fewer arm's-length resales, which makes appraisals harder to support, and some conventional lenders take a closer look at HOA rental caps before they will underwrite. Buyers should ask their agent to pull the recent sale-versus-rental mix on any subdivision they are considering.
The flip side is opportunity. Several of the large rental funds have been trimming their Atlanta holdings, and those homes come to market as ordinary listings, usually with a fresh coat of paint and a builder-grade kitchen. They are negotiable, they close cleanly, and they rarely draw bidding wars.
Property Taxes Changed and Counties Did Not All Follow
Georgia's floating homestead exemption from the 2024 legislative session capped how fast the taxable value of a homesteaded property can rise, tying increases to inflation rather than to whatever the assessor's model produces. That was the biggest shift in Georgia property tax policy in years, and it matters most in fast-appreciating areas.
The catch is that counties, cities, and school systems were allowed to opt out. Several metro Atlanta jurisdictions did exactly that, so two houses across a county line can be treated very differently. Buyers should confirm the status in the specific taxing jurisdiction before assuming their bill is capped.
Assessment notices go out in the spring and early summer, and the appeal window is short once yours arrives. If you bought recently and the assessed value came in above your purchase price, your closing statement is the strongest evidence you will ever have, and appeals on that basis succeed often.
What Inspections Turn Up on Atlanta Houses
Red clay is the local villain. It holds water, expands, and pushes against foundations and basement walls, which is why so many Atlanta inspection reports flag grading and downspout drainage. The fix is usually cheap, and the consequence of ignoring it for a decade is not.
Age of the housing means a predictable list of issues by era. Ranches from the 1960s and 1970s can have aluminum branch wiring or original cast iron drain lines, homes from roughly 1978 to 1995 may still have polybutylene supply pipes, and any of it can complicate an insurance binder. Ask the seller what has been replaced and when, in writing.
Termites deserve their own conversation. A transferable termite bond is standard in Georgia and worth confirming before closing, since the humidity and the tree canopy make this one of the more active termite regions in the country.
Insurance and Storms Belong in the Budget
Homeowners insurance in Georgia has repriced upward, driven by hail and wind losses across the northern part of the state and by higher rebuild costs. Quotes on a house with a 20-year-old roof come back dramatically worse than quotes on the same house with a five-year-old roof, and some carriers will only write actual cash value coverage on older shingles.
Get a quote during your due diligence period rather than the week before closing. A $2,600 annual premium and a $4,200 annual premium change what you can afford, and finding out late has killed plenty of Atlanta contracts.
Tree cover is the other line item. Atlanta's canopy is one of its best features and one of its more expensive liabilities, since removing a large water oak leaning toward the roof runs into the thousands and the city requires permits for many removals.
The Forecast for the Rest of 2026
Expect more of the same through the fall: flat to slightly softer pricing, longer marketing times, and sellers carrying more of the transaction cost. Job growth across logistics, healthcare, film, and the Midtown tech corridor keeps demand steady enough to rule out a sharp decline, and Hartsfield-Jackson continues to anchor corporate relocations that other metros compete for.
The variable that would change everything is mortgage rates. A meaningful drop pulls sidelined buyers back into competition for the same listings, and Atlanta's affordability relative to Boston or Los Angeles means that demand arrives quickly when financing gets cheaper. If you want to see how other metros are working through the same adjustment, our housing market coverage from around the country tracks the same questions city by city.
The long-run case here has not weakened. Land supply on the metro edge, a diversified employment base, and continued in-migration from higher-cost states have supported values through every previous slowdown.
Advice That Fits This Market
Strategy in a flat market looks different from strategy in a rising one, and plenty of buyers and sellers are still running the 2021 playbook. The right approach this year rewards patience on one side and realism on the other. Both start with reading the specific submarket instead of the metro headline.
Financing is where the real money is right now. A seller-funded 2-1 buydown can save a buyer several hundred dollars a month in the first two years, and it costs a seller less than an equivalent price cut. Ask for it by name.
If You Are Buying
Shop the concession, not just the price. On a house that has been listed 60 days, a request for closing costs plus a rate buydown often lands better than a lowball offer, and it leaves the seller's comparable sale intact.
Use your due diligence period. Georgia contracts give you a real window to inspect, quote insurance, verify the tax situation, and walk away, and buyers who treat it as a formality are the ones who get surprised in month three.
If You Are Selling
Price to the last 60 days of sales in your subdivision, not to what your neighbor got in 2022. The first two weeks of listing traffic are the most valuable exposure you will get, and a price correction after that only reaches a smaller audience.
Spend money where inspectors look. A roof certification, a serviced HVAC system, corrected drainage, and a current termite bond remove the objections that turn into repair credits later.
Frequently Asked Questions
Are Atlanta home prices going down in 2026?
Metro-wide prices are roughly flat, moving within a few percent of last year rather than falling in any meaningful way. Individual submarkets differ, and outer counties with heavy new construction have seen more downward pressure than intown neighborhoods near the BeltLine.
Is Atlanta a buyer's market right now?
In most of the metro, yes, though it depends on price point. Homes above $700,000 and homes needing work sit the longest, while updated properties under $400,000 in strong school zones still move quickly and occasionally draw multiple offers.
How much does homeowners insurance cost in metro Atlanta?
Premiums vary widely by roof age and claims history, and the difference between a new roof and a 20-year-old roof can be well over $1,000 a year on the same house. Quote it during due diligence, because some carriers will not write full replacement cost coverage on older shingles at all.
Do investors still buy houses in the Atlanta suburbs?
Yes, though the large funds have slowed their acquisitions and several have been selling metro Atlanta inventory instead. Clayton, Henry, and south Fulton still carry the highest concentration of corporate-owned rentals, which is worth checking before you write an offer in one of those subdivisions.
Which Atlanta suburbs give the most house for the money?
Henry, Paulding, Douglas, and parts of Gwinnett consistently deliver the largest square footage per dollar in the metro, often $100,000 below a comparable house in north Fulton or Forsyth. The tradeoff is commute time, since most of those areas depend on I-20, I-75, or I-85 to reach the job centers.